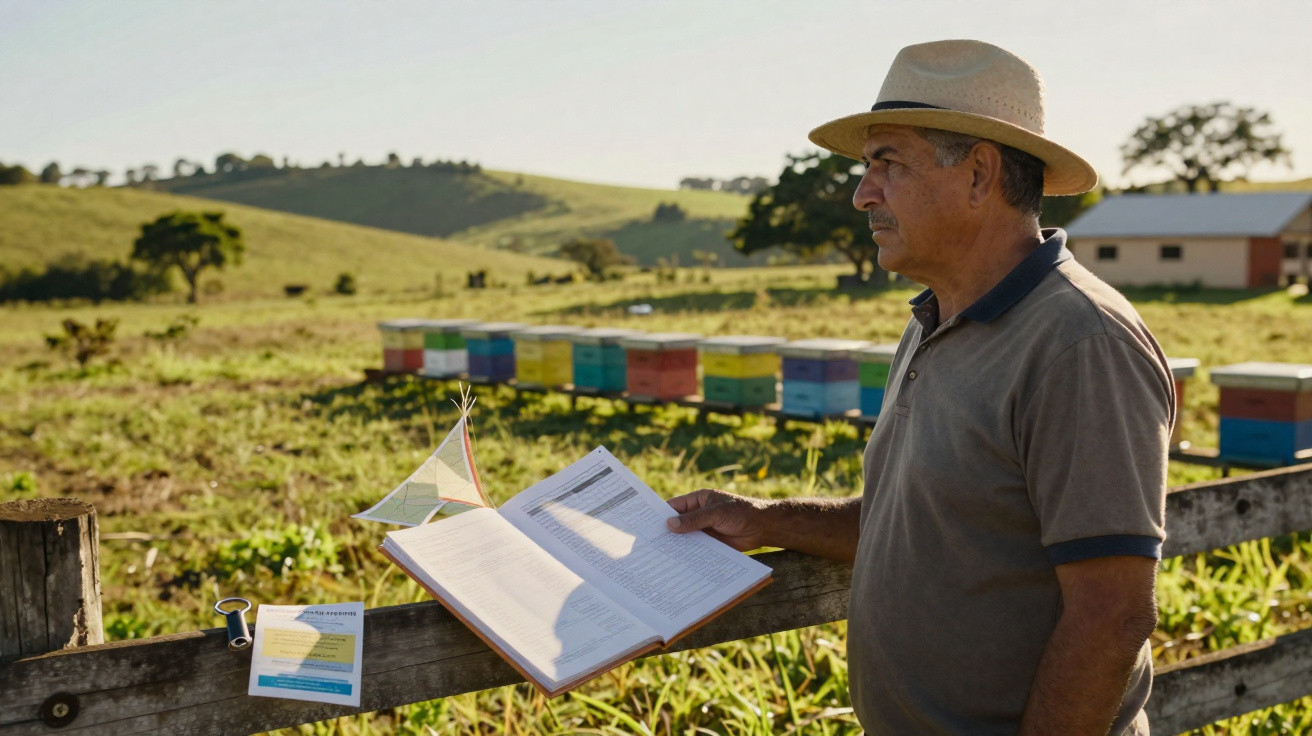
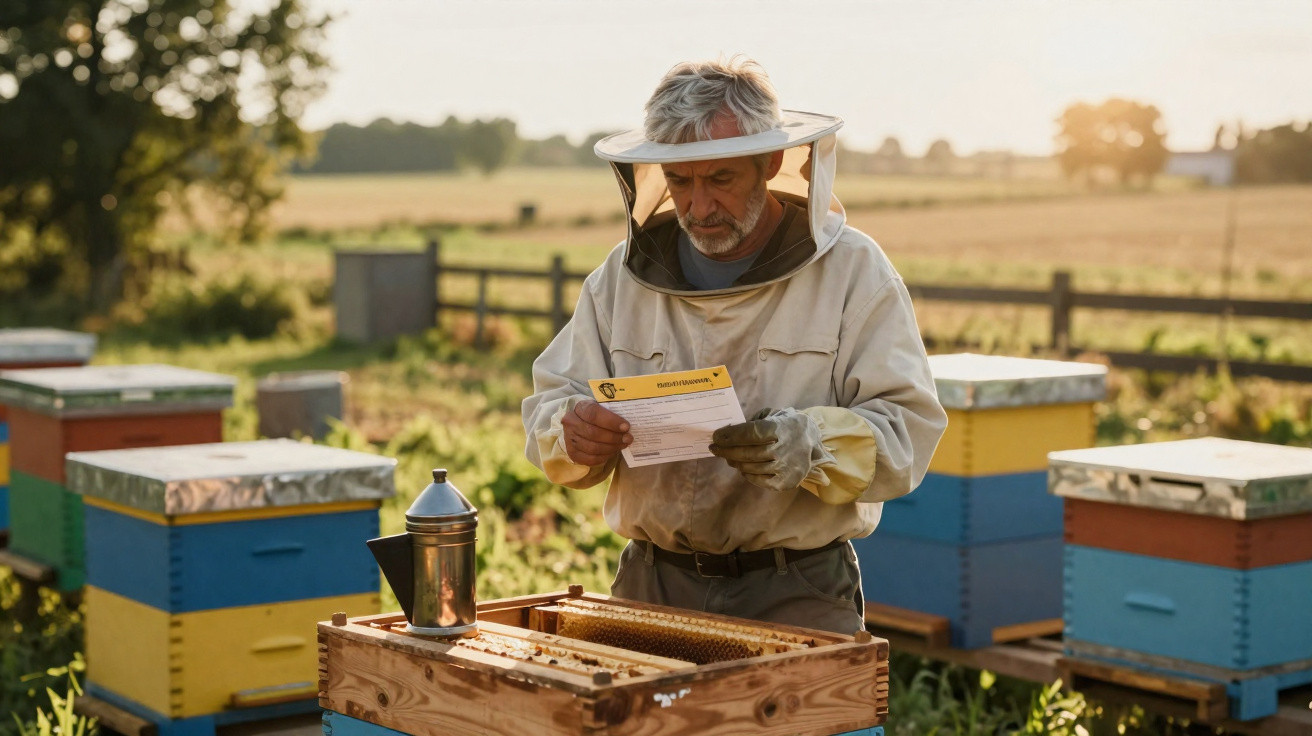
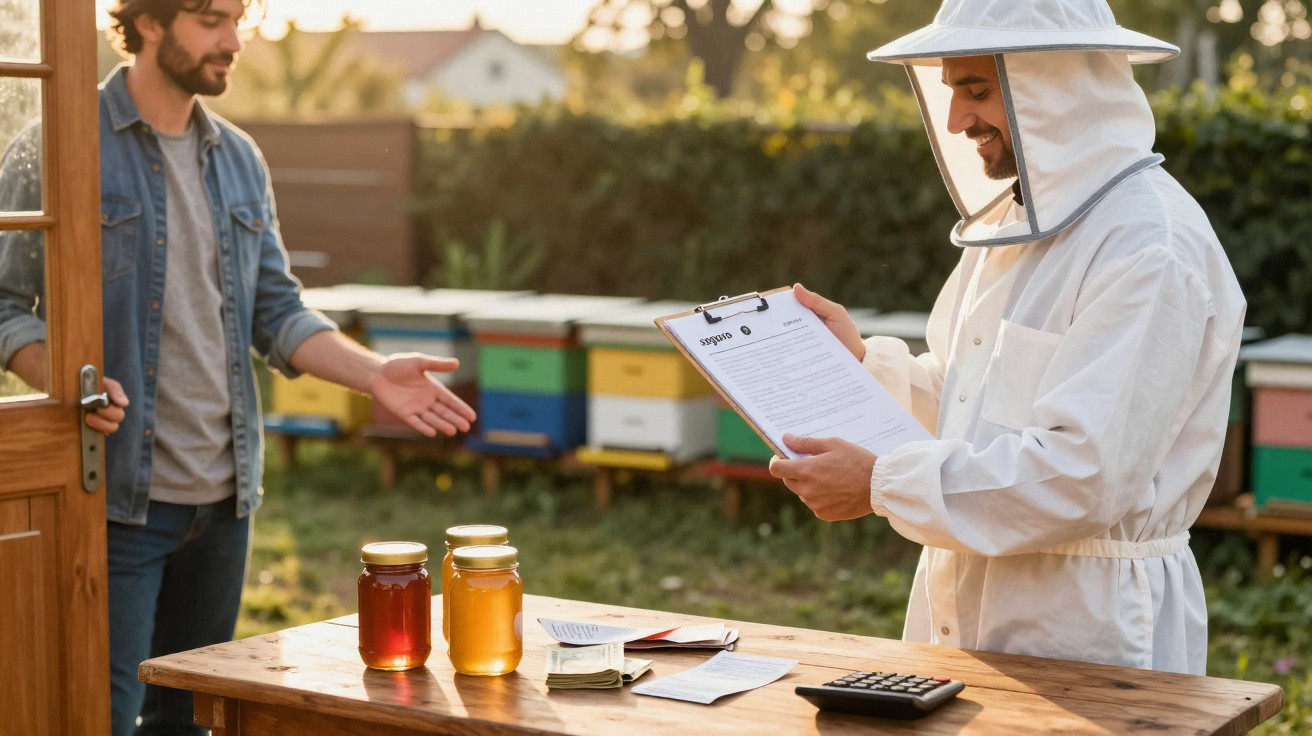
The morning the letter arrived, the bees were the busiest workers on the property. The retired owner sat on his deck with a coffee, watching the hives beside the fence catch the early sunlight. The hives did not even belong to him. A friendly local beekeeper had asked to keep them there “for the blossoms”, offering a couple of jars of honey each year in return. It seemed like the sort of neighbourly gesture people celebrate when leaving city life behind.
Then an envelope from the tax office appeared on the kitchen table.
Those seemingly innocent wooden boxes had, on paper at least, changed his “peaceful plot” into a taxable farm.
When a peaceful plot is classified as a farm
For thousands of retirees, the ambition is straightforward: sell the large home, purchase a few acres, take a deeper breath and watch the year unfold. Perhaps a nearby farmer can graze a handful of sheep there, or a beekeeper can place several hives in a far corner. It feels like caring for the land rather than conducting business.
That is why it can be such a shock when the local authority or tax board decides that the hives, or a modest area of hay, mean the property is now in “agricultural use”. With that description comes an entirely different tax system, one most people never expect to affect their slow afternoons and wildflower-filled land.
A retired couple in their late sixties, living in a semi-rural county, learned that lesson the hard way. They had let a beekeeper put ten hives in their rear field. There was no official rent and no written contract-only a friendly handshake and a few jars of honey at Christmas. To them, it was a charming, almost old-fashioned arrangement.
After two years, they received a reassessment notice. Their land had been reclassified as being used for commercial agricultural activity. This resulted in a revised tax calculation, as well as back taxes, penalties and interest. They did not sell honey, own the bees or hold a business licence. Nevertheless, the law treated them as though they operated a small farm. The beekeeper was not liable; the landowners were.
The tax office’s reasoning is detached but consistent: tax follows land use, not sentiment. If a property is used to create income-even where somebody else receives that income-it may be subject to farming rules. Assessors consider the physical activity taking place: hives, animals, crops and buildings. Their first question is not who receives the money.
As a result, a retiree thinking, “It’s just a couple of hives” can find themselves facing legislation intended for commercial orchards, grain farms and full-time ranches. The law is usually less concerned with the owner’s circumstances than with the fact that a business is operating on their land. That is the retirement trap.
Protecting your land before a tax bill arrives
The low-key but sensible approach is to view every “neighbourly favour” involving your land as a small business decision. That does not mean turning away the beekeeper; it means asking unexciting questions before the hives appear. Who owns the equipment? Who has insurance? Who reports the income? How will the land be described in formal documents?
A useful measure is to put a brief, clearly worded agreement in place. It should state that your land is “licensed” or “permitted” for temporary use, that the operator retains ownership of the hives or livestock, and that all agricultural income belongs solely to them. Such a document will not automatically remove every tax risk. However, it creates a record showing that you are the host rather than the farmer.
Most people never take this step. It can feel uncomfortable, as though asking a friend to sign paperwork spoils the atmosphere. In truth, nobody handles every favour this formally all the time. You agree to the beekeeper’s request because you want to be helpful, encourage pollinators or simply participate in something wholesome.
Then the regulations arrive and spoil the arrangement. The familiar error is failing to establish in advance whether the county connects agricultural activity on your land with farm classifications. Another mistake is allowing someone to register a “farm address” at your property, or to include your parcel in their business records without understanding the consequences. That is how several apparently harmless hives can become proof of a commercial enterprise in the eyes of the authorities.
“I thought I was just sharing space with the bees,” one retired teacher told a local newspaper. “Turns out I was the one sharing the tax bill.”
- Review local agricultural-use rules before anybody installs hives, pens or growing plots on your property.
- Use a short written agreement confirming who operates the business and who declares its income.
- Find out whether the arrangement could alter the land-use classification or property-tax status.
- Speak to a tax professional or agricultural advisory office early, rather than waiting for a reassessment notice.
- Retain photographs, dates and basic records showing how the land is genuinely used, in case you must dispute a decision.
Land ownership when no favour is “just a favour”
Retirement was once presented as a move towards an easier life: a smaller home, fewer concerns, some gardening and perhaps bees humming at the woodland edge. That vision confronts a very different reality when rules designed for industrial agriculture meet small-scale, neighbourly land use. The distance between what seems fair and what has legal significance can be considerable, and retirees are often the first to be caught in it.
The simple reality is that those wooden boxes and their soft hum may represent both rural calm and a legal trigger you never anticipated.
Perhaps the real modern skill of growing older on your own land is being able to say, “I’d love to help-but I need to see how this plays with my taxes first.” It is neither romantic nor Instagrammable, but it is quietly protective. The bees will still locate flowers, and the beekeeper can find another fence line if necessary. Your responsibility is to protect your final major asset: the land beneath your feet and the retirement it is meant to support.
| Key point | Detail | Value for the reader |
|---|---|---|
| Land use, rather than profit, determines tax status | Authorities assess what occurs on your property, even when you receive no income from it | Helps you identify concealed tax risks in “friendly” arrangements |
| Written agreements are important | Straightforward documents setting out responsibilities and income can support your position | Makes it less likely that you will unintentionally be treated as operating a farm |
| Ask before the hives arrive | Check local rules, consult advisers and record the actual use of the land | Allows you to retain your peaceful plot without unexpected tax bills |
FAQ:
- Question 1: Can I be taxed as a farm even if I make no money from the bees kept on my land?
- Question 2: Who is generally responsible for income from honey or farm produce-the landowner or the operator?
- Question 3: Can a straightforward handwritten agreement with a beekeeper or farmer carry any weight?
- Question 4: What should I ask the tax office or assessor before allowing someone to use my land?
- Question 5: Is it safer simply to refuse hives and small farming projects on my retirement property?
Comments
No comments yet. Be the first to comment!
Leave a Comment