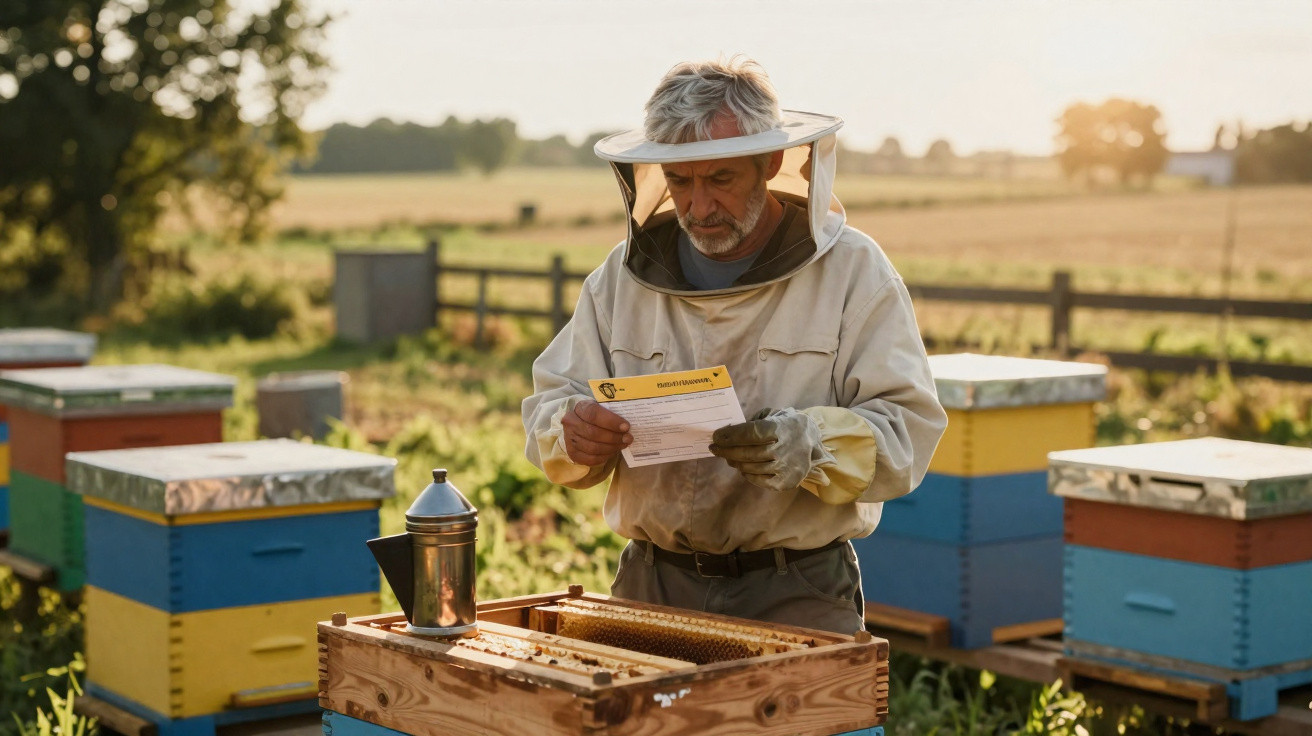
On a cold April morning, Paul, a retired electrician, walks beside a field that is not his.
On one side stands a damaged fence; on the other, twenty softly buzzing hives, piled up like pastel-coloured filing cabinets.
He draws his jacket closer as sunlight reaches the boxes and stirs the thousands of bees he has cared for over the years.
What had been a borrowed patch of scrubland and brambles became his retirement ambition: honey, fresh air and, perhaps, a modest extra income if all went particularly well.
Then the letter came.
It was an official brown envelope containing phrases such as “agricultural activity”, “undeclared income” and “assessment”.
In official terms, those unassuming hives had transformed his “little hobby” into a taxable agricultural operation.
He looked at the figures. The authorities were unmoved when he kept saying, “I’m not making any money from this.”
Paul believed there had been a mistake. The tax office believed it was applying the law.
That was the start of the dispute.
When a few hives on borrowed land become an “agricultural business”
Paul began in the way many people discover beekeeping later in life.
He bought three hives, then five, then ten, and asked a local farmer whether he could place them by the hedgerow “just for pollination”.
There was no rent and no written agreement, only a handshake at a muddy gate.
The farmer benefited from improved pollination for clover and fruit trees. Paul gained a place for his bees that was not his cramped back garden.
Then he did what many delighted beekeepers do.
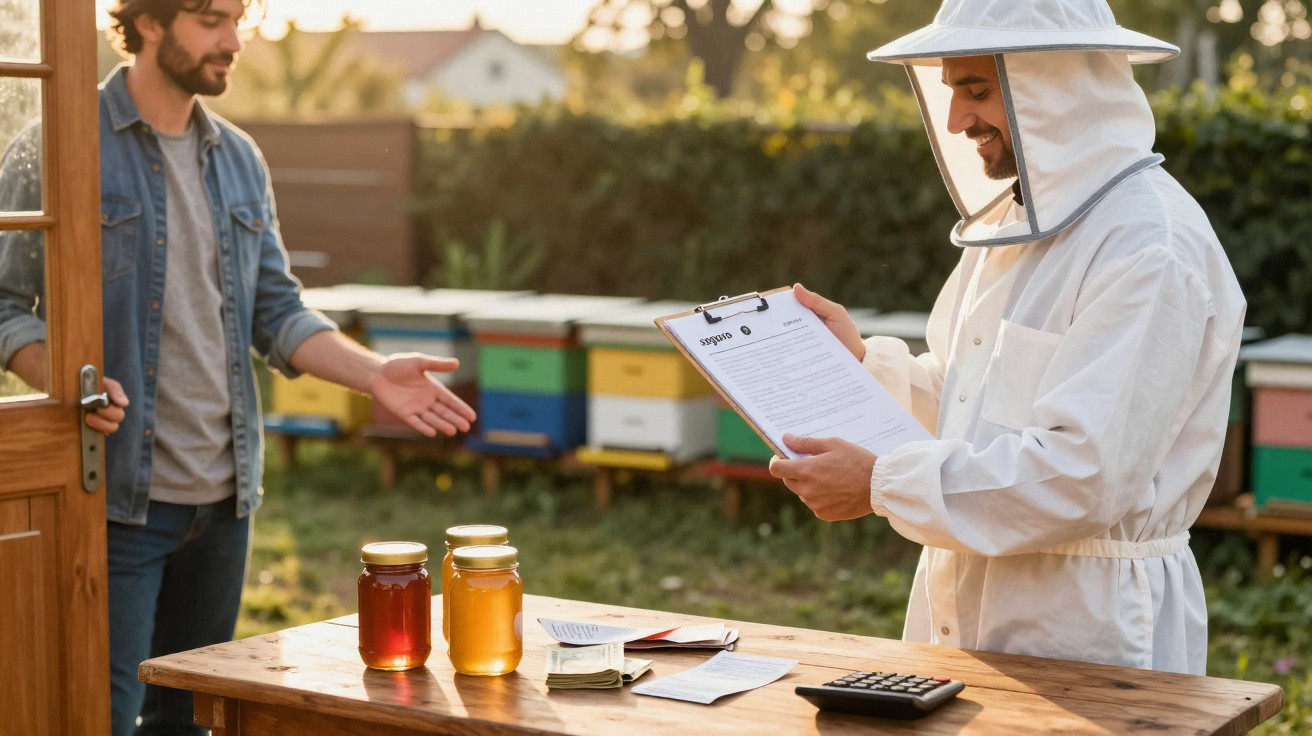
He advertised jars of golden honey on Facebook and local classified listings, describing them as “Suggested donation, not for profit.”
Several neighbours handed over cash, and a small organic shop asked whether he could supply honey regularly.
That was enough to bring the system’s attention.
During one of the shop’s routine checks, a detail entered on a form caused Paul’s name to surface.
“Do you have a farm registration number?” the shop owner asked one day, almost in passing.
Paul laughed and shrugged. “I’m retired, this is just for fun.”
But because the shop needed evidence for its own accounts, it recorded his name and address regardless.
Months afterwards, the tax office connected his honey supplies, the borrowed land and the hive numbers declared to the local beekeeping association.
Once someone has more than a certain number of hives, local rules class them as an agricultural producer.
Not a hobbyist. Not a retiree. A producer.
That alone was sufficient for an agricultural tax demand to arrive at his home, including penalties for “undeclared activity” spanning several years.
When Paul phoned, he made what he considered a straightforward point: “I’m not making any money from this.”
He described the jars he had given away, the equipment paid for from his own savings and the fact that his costs exceeded his takings.
To him, the position seemed self-evident.
To the authorities, the reasoning was more impersonal.
Rural tax rules do not begin with how you feel, your age or your insistence that you are making a loss.
They assess set criteria: hive numbers, how regularly honey is produced, whether sales are visible and even whether those sales are very small.
Where the relevant boxes are ticked, officials label it “agricultural activity” and treat it in the same category as growing wheat, keeping sheep or making wine.
The law was not claiming that Paul had become wealthy.
It was simply saying that, at this scale, he had entered the system.
Whether his bank balance reflected that or not.
How small-scale beekeepers can protect themselves before the taxman calls
One dull but practical measure might have spared Paul a great deal of worry: recording his hobby as though it were a very small business from the outset.
That does not mean creating a large company; it simply means keeping written records.
Use a basic notebook or spreadsheet to note dates, jars sold, jars given away, money received and money spent.
Retain receipts for equipment, sugar, treatments and fuel.
Take photographs of the hives over time, with dates and labels.
This unobtrusive record can become a form of protection.
If the authorities investigate years later, you will not need to piece together events from coffee-stained envelopes and imperfect recollections.
Instead, you can clearly demonstrate that your “activity” has not been profitable and was never intended to operate as a genuine farm, however professional the bees may appear.
Many people know how easily a passion can slowly become something that resembles work.
You tell yourself, “It’s just for friends,” then somebody offers to pay, a shop contacts you and you are too pleased to refuse.
The danger lies in assuming that the authorities will see it as a hobby simply because you do.
The law does not measure feelings; it looks for indicators such as regular deliveries, labels, repeated social-media advertising and a recognisable name on the jars.
In truth, few people study every tax booklet or agricultural guide before placing two beehives in a field.
Yet this is precisely how modest retirement ambitions can come into conflict with large, impersonal regulations.
The gentlest error is often the most widespread: believing that “I’m not making any money” is a magic phrase.
For tax inspectors, it merely begins the discussion rather than ending it.
“I thought common sense would count,” Paul told me, standing between his hives.
“I’m not a farmer. I’ve never filled in a single form for this. I’ve just tried to keep bees alive. Now they tell me I should have registered, declared, anticipated…”
He broke off and shrugged. “If I’d known the rules, I would have done things differently.”
Speak to a local adviser early
Ask a farmers’ union, beekeeping association or small-business adviser how beekeeping is classified in your area. Small points, including the exact hive count or whether you supply shops, can alter the position completely.Put an agreement in writing with the landowner
Even a single-page document signed by both parties, confirming the land loan (no rent, no agricultural tenancy, beekeeping only), may help show inspectors that this is not a concealed farm tenancy.Choose your limit beforehand
Set your own upper boundary: “I won’t go above X hives or Y jars sold per year unless I formalise things.” This prevents enthusiasm from taking you directly beyond a legal threshold.Keep money separate from goodwill
It may feel pleasant to “give” honey while accepting a small amount of cash. In official records, repeated cash payments are still income. If you genuinely want it to remain solely a hobby, consider accepting no money at all or only very occasional bartering.Retain evidence of losses
If you do cross into the “activity” category, thorough records of expenditure can show the real picture: your bees are a labour of love, not a concealed source of riches.
Law versus life: what this beekeeper’s tax dispute reveals about retirement dreams
This is not only a story about bees or one determined tax inspector.
It concerns the uncertain boundary between leisure and work, and the point at which a peaceful retirement ambition can appear to the state to be employment.
Many retirees move towards that boundary without realising.
A small market garden, a handful of guest rooms, a craft workshop in the garage or jars of jam sold at the village fair can all fit the pattern.
In everyday life, these projects can feel like ways to remain active, useful and connected.
In administrative terms, they can be potential “activities”, each with its own codes, classifications and duties.
The more society encourages retirements that are active and entrepreneurial, the more these grey areas expand.
And the more painful it can be when a tax demand disrupts something that was expected to represent freedom.
| Key point | Detail | Value for the reader |
|---|---|---|
| Know when a hobby becomes “activity” | Authorities commonly apply thresholds: number of hives, sales volume, regularity of deliveries and product visibility. | Helps you identify early when you may be entering a legally taxable area. |
| Paper beats memory | Simple records of purchases, jars sold or given away, and land use can prove your actual circumstances years afterwards. | Gives you a stronger position if you face a tax review or need to challenge a classification. |
| Talk before you expand | A brief discussion with a local adviser or beekeeping association can explain your duties before you grow. | Prevents your retirement project from becoming an unforeseen tax problem. |
FAQ:
- Question 1 Does beekeeping always count as an agricultural activity for tax purposes?
- Question 2 Can I avoid tax problems by giving away honey and accepting “donations”?
- Question 3 Does it matter that the land for my hives is loaned rather than rented?
- Question 4 What should I do before increasing my number of hives in retirement?
- Question 5 Can I challenge a tax assessment if I genuinely never made a profit?
Comments
No comments yet. Be the first to comment!
Leave a Comment