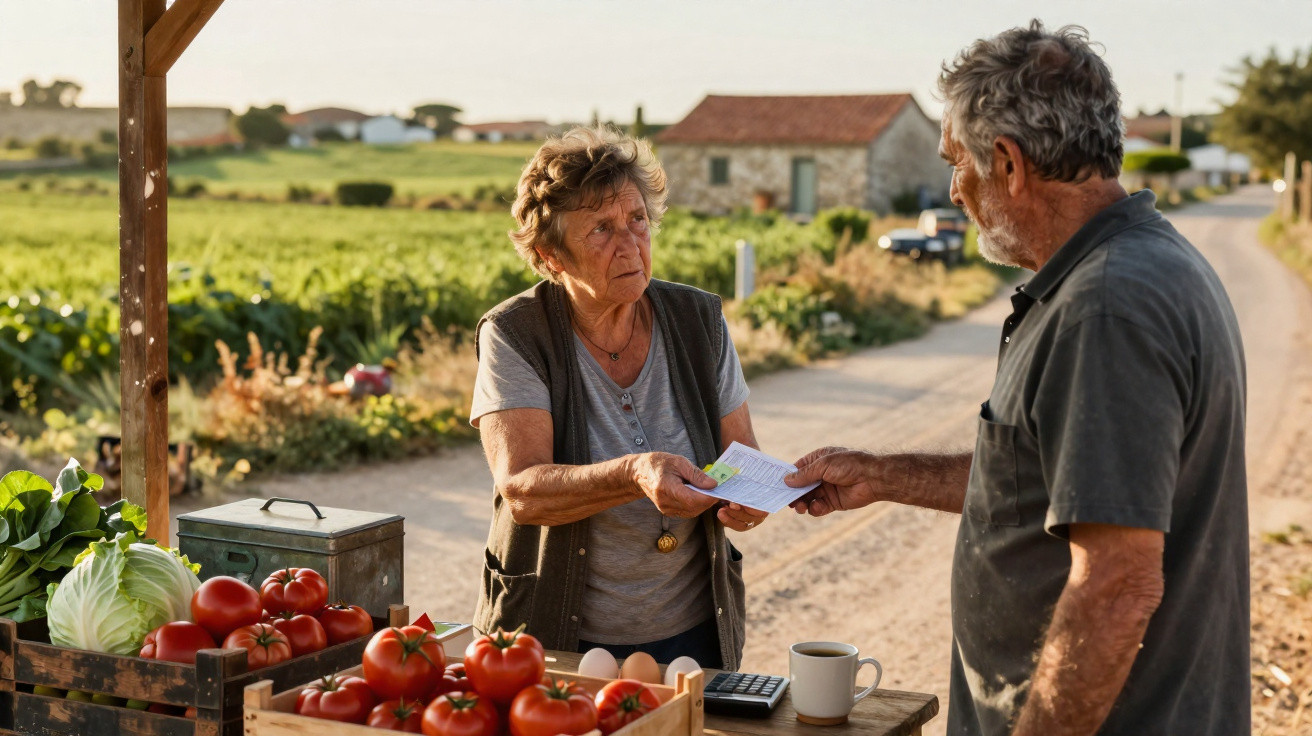
On market days, they are often the first people you spot: the retired pair in worn trainers, lifting crates of tomatoes from a dusty car and sharing a laugh with the young farmer fighting to keep a small holding viable. They are not doing it for payment. They help because they were raised with soil beneath their fingernails, because their parents did likewise, and because lending a hand on a farm feels as natural as breathing.
Recently, though, a warning has travelled between market stalls and across garden fences: “Careful, you’ll get hit with agricultural taxes if you keep doing that.” Some pensioners have begun turning down requests for help. Others disappear into the shed when an inspector’s vehicle drives past.
The issue now looms like a storm: should retirees stop supporting small farmers simply to avoid being penalised by the tax system?
When solidarity begins to seem suspicious
At dawn in almost any rural village, the same quiet routine plays out. A retired neighbour feeds chickens for a young farmer juggling two jobs. A widower helps turn hay after a local farmer injures his back. A former agricultural worker takes the tractor out “just for the harvest”.
This sort of everyday support has traditionally gone unnoticed and has seemed almost self-evident. It is neither declared nor paid as a proper wage, and may receive little more than a crate of potatoes or a bottle of wine in thanks. No one described it as “undeclared work”; it was simply community.
Now, however, those ordinary acts are being scrutinised. What once appeared to be generosity can suddenly appear, on paper, to be taxable labour.
Consider Pierre, 71, who lives in a small valley where dairy cows still outnumber tourists. For the past four summers, he had assisted his neighbour, a young farmer attempting to manage 40 cows alongside a mountain of paperwork. Pierre drove the tractor, kept watch during overnight calving and helped with silage. His reward? A few cheeses, money for fuel and companionship.
During a routine inspection last year, officials noticed inconsistencies: periods of “occasional help” that appeared a little too frequent. They began asking questions, raised the possibility of undeclared work and referred to potential contributions and back taxes.
Pierre returned home looking pale. The following day, his neighbour arrived in distress after two heifers had escaped, but the older man remained at his doorstep with his hands in his pockets. “Sorry, I can’t anymore. Too risky.”
Legally, the principle is straightforward: any productive activity that is regular and organised may be treated as agricultural work and may attract tax and social contributions. Receiving a pension does not automatically exempt someone from the rules. Tax authorities see the hours worked, the value produced and the potential for fraud.
In practice, the situation is far less clear-cut. The divide between helping a friend and concealed employment is narrow, and can shift according to an individual inspector’s interpretation. Infrequent assistance is generally tolerated, whereas regular support can start to resemble employment. Cash payment crosses a further boundary.
These rules are intended to safeguard workers and prevent abuse. Yet when legislation designed for factories meets the realities of small farms and big-hearted retirees, the outcome can seem irrational, even harsh.
Helping small farmers without falling into a trap
The first useful step is to establish exactly what form your help takes. Short-term, irregular and occasional assistance is seldom an issue. Spending every day of the harvest period driving a tractor, year after year, is a different matter.
A practical way to judge it is to view the help as you would a visit. A few hours now and then, particularly in response to an unexpected problem, remains within a zone of neighbourly solidarity. Once it turns into scheduled shifts with a defined role, it starts moving into employment territory.
Retirees can also choose tasks that are not directly productive: taking the farmer into town, looking after children during lambing, or cooking for the harvest crew. Such support still matters and can still transform someone’s week.
The greatest mistake is assuming that everything will be fine if you “stay under the radar”. That approach is a direct route to uncomfortable encounters and sleepless nights. In truth, hardly anyone reads every tax rule before assisting a neighbour.
Even so, certain warning signs should not be overlooked: regular cash-filled envelopes, discussions about working “off the books”, or a clear timetable such as Monday to Friday, 8 to 12. At that point, it is no longer merely a kind gesture; it is work without protections.
If discussing what you do leaves you with a knot in your stomach, that often suggests something is wrong. You do not have to stop helping altogether, but you may need to rethink how, when and why you provide support.
Sometimes, the most protective sentence a retiree can say to a farmer is: “I want to help you, but we’re going to do it in a way that doesn’t put either of us in trouble.”
- Favour brief, irregular help
A harvest weekend, clearing up after storm damage or emergency animal care are demanding but short-lived situations that rarely draw questions. - Restrict or avoid direct cash payments
Gifts in kind, shared meals and reciprocal services generally sit in a more informal, tolerated area. Tax law mainly targets organised, repeated undeclared work. - Ask about simplified legal options
Some areas provide simplified seasonal contracts, occasional-worker schemes or exemptions for short-term assistance. A brief appointment with a local agricultural office can avert years of concern. - Maintain your independence
Do not use the farm’s email address, sign official paperwork or represent the business. You are a friend, not an employee. - Discuss boundaries openly
Explaining, “I can help two mornings a month, not more” offers protection and encourages the farmer to consider their genuine labour requirements.
Agricultural taxes, dignity and rural life
This debate raises a broader question: what sort of countryside do we want to inhabit? One where every action is counted, taxed and declared, or one where some forms of solidarity are recognised as part of the social fabric?
Many retirees have no wish to return to “work”. They want to be useful, share their knowledge and remain connected to the seasons’ rhythms. Farmers, meanwhile, often depend on these unseen helpers when their bank balance is low and the milking machine fails.
If retirees pull back entirely because they fear penalties, small farms may lose a discreet yet vital network of support. Equally, it would be dishonest, both morally and legally, to pretend that no problem exists where work is clearly disguised.
| Key point | Detail | Value for the reader |
|---|---|---|
| Understand the legal grey zone | The distinction between occasional help and organised, repeated work | Helps avoid unintended tax issues while continuing to offer support |
| Choose safer ways to help | Prioritise irregular tasks, non-core farm work or simplified legal schemes | Enables retirees to help small farmers without persistent anxiety |
| Establish clear limits and communicate openly | Agree the frequency, task types and non-cash compensation | Protects relationships and promotes fair, sustainable support |
FAQ:
- Question 1 Can a retiree occasionally help a farmer without paying agricultural taxes?
- Question 2 At what point is help treated as “undeclared work”?
- Question 3 Does payment in kind, such as vegetables, meat or cheese, create a legal risk?
- Question 4 Are there straightforward legal arrangements allowing a farmer to employ a retiree part-time?
- Question 5 What should a retiree do if an inspection is announced after they have been helping regularly?
Comments
No comments yet. Be the first to comment!
Leave a Comment