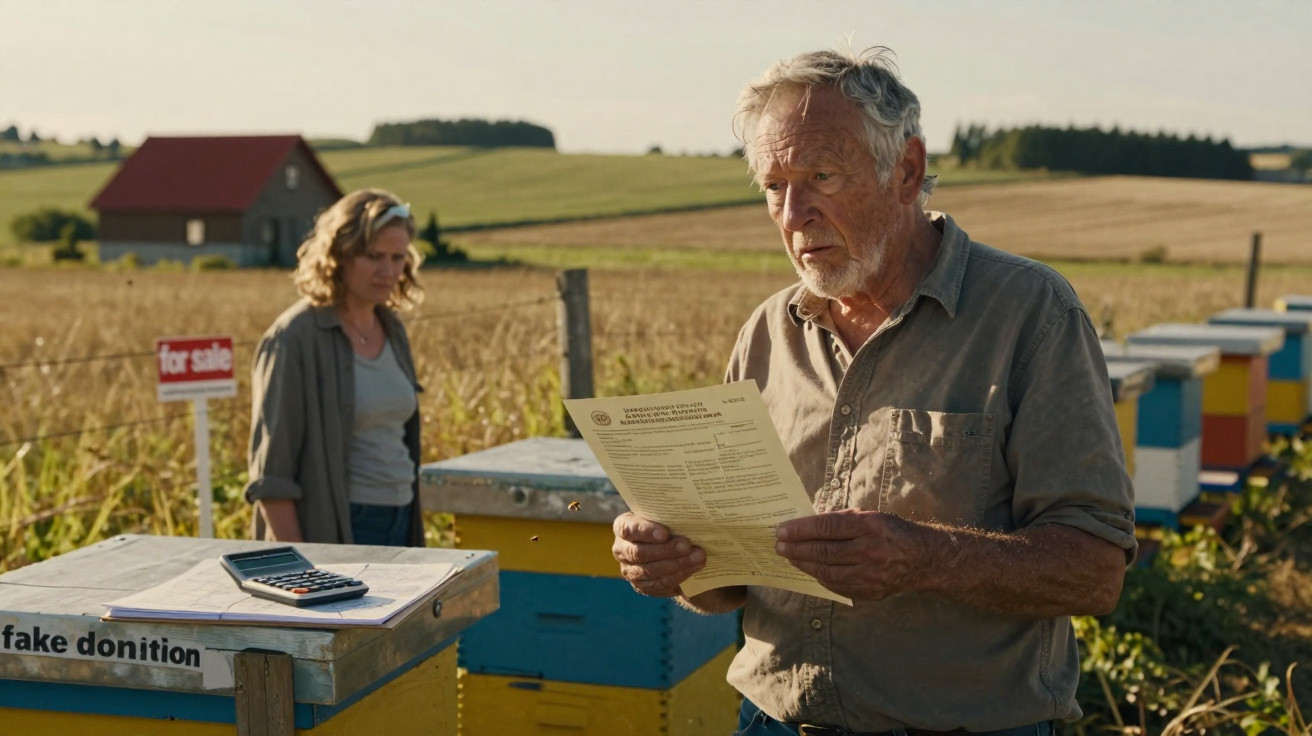
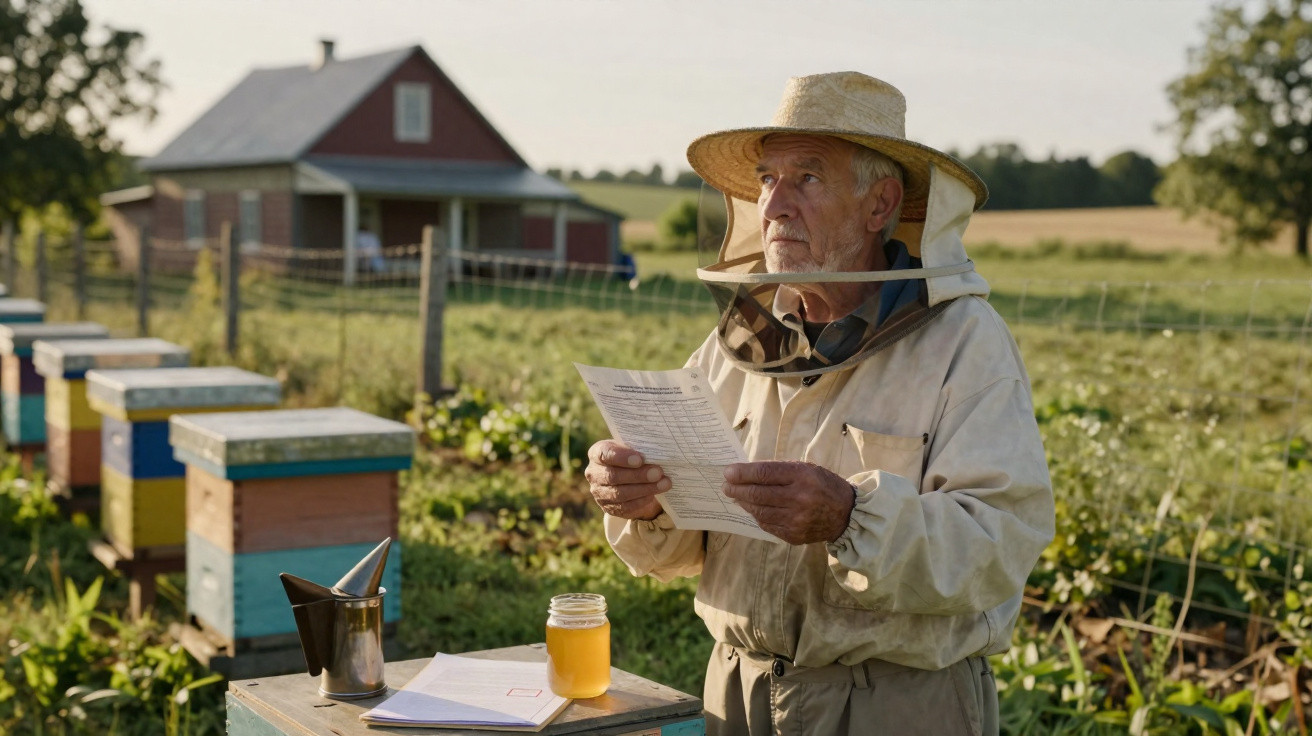
On a foggy October morning in rural western France, with tractors leaving sluggish ribbons of mud across the lanes, 72-year-old Jean-Marc opened his postbox and felt a knot form in his stomach. Mixed in with supermarket leaflets and a postcard from his granddaughter sat a heavy brown envelope from the tax authorities. He knew immediately what it concerned: several years earlier, he had “gifted” a patch of scrubland to a younger neighbour, allowing him to set up beehives, transform brambles into bee pastures and make practical use of ground that had produced little beyond thistles.
Jean-Marc had believed he was simply doing a kind thing.
The tax authorities, it seemed, took an entirely different view.
When a kind gesture becomes a taxable “scheme”
French pensioners such as Jean-Marc were raised with a straightforward understanding: land changes hands, often on the strength of a handshake and occasionally over a glass of red wine at the kitchen table. A notary, a plan or a tax calculation was not always thought necessary. You let a neighbour establish beehives. You gave a friend part of an old field so that they could put up a modest timber shed. It was not regarded as a “wealth transfer”, let alone “speculation”.
Yet these understated rural customs are now coming up against a state that examines every square metre closely. If a field rises in value, planning rules change or tax officials compare cadastral maps with declarations, an old favour can suddenly appear to be a taxable transaction.
For Jean-Marc, the land had been recorded as near-worthless pasture at the time he “gave” it away. A few years afterwards, the local authority discreetly re-zoned part of the area, increasing land values. His neighbour enlarged the bee pastures, fitted out a small workshop and even spoke publicly about launching a rural honey shop. Local officials welcomed the development, sharing photographs of the “revitalized countryside” on social media.
Those same posts were seen by a tax inspector, who noticed that the transfer, registered as a modest “donation”, seemed inconsistent with the plot’s newly apparent potential. The neighbour was asked to provide documents. Jean-Marc received the brown envelope. The state now viewed the “gift” as under-declared and potentially as concealed speculation between friends.
The tax reasoning is starkly straightforward. A free transfer between people who are not close relatives should be taxed as a gift, using the land’s true value. Where that value has been understated, or where the land rapidly supports a profitable activity, the administration may assume that somebody sought to avoid scrutiny. What appeared to be bee pastures can suddenly be interpreted as a minor property venture.
For pensioners who own a few hectares they scarcely use, this change can feel like a snare. The terminology is severe: reclassification, abuse of law and hidden capital gain. The emotional impact is more severe still. How can helping a neighbour keep bees become a suspected financial arrangement?
How French tax authorities identify “fake gifts”
A recurring situation is emerging in French villages. An older landowner, frequently a widow or widower, regards their land as a burden. Taxes eat into their pension, fencing deteriorates and brambles spread. Then a younger farmer, beekeeper or friend with an ecological project offers to put it to use. The answer may seem self-evident: transfer a section of the plot for one symbolic euro, or make a simple donation so that the project can begin quickly.
From a personal perspective, this is entirely sensible. Seen from a tax inspector’s desk, however, it may resemble an attempt to sidestep registration charges, gift tax or capital gains tax. The same field is being viewed by two sides that see very different things.
Consider the recent growth in bee pasture projects across France. Supported by local councils and environmental schemes, numerous small-scale beekeepers have emerged, often with limited funds. Rather than commit to lengthy leases or costly purchases, they depend on informal land arrangements. “Take this old meadow, do something useful with it, I don’t need it anymore,” says the pensioner. Honey is produced and perhaps a modest income follows. Once land is cleared, fenced and made accessible, it becomes more valuable.
This is also where algorithms enter the picture. Tax departments compare property databases, agricultural subsidies and local business registrations. A new venture on a formerly neglected plot triggers a modest digital alert. If the earlier transfer was undervalued or took place shortly before the project began, doubts increase: was it genuine generosity, or a shrewd method of avoiding tax on an asset clearly expected to appreciate?
The administration can legally reclassify the arrangement. A transaction declared as an ordinary donation may instead be considered a disguised sale, resulting in back taxes, penalties and late-payment interest. The purpose is to uncover genuine schemes in which land passes through friends or distant relatives before being sold at a high price, with the proceeds shared and tax obligations avoided.
However, the net catches widely. People such as Jean-Marc are swept up with genuine speculators. They seldom have advisers, sign the documents suggested by the notary and follow village traditions. Years later, they discover concepts such as “fair market value at the time of transfer”, while their “gift” is recalculated at three times its original estimate. One brown envelope can wipe out years of careful, modest savings.
Helping a friend with land without jeopardising your retirement
There is a less exciting but far safer route that can prevent considerable distress. Before giving away a parcel of land, even land that looks like unusable scrub, obtain a genuine independent valuation. Do not rely on an assumption or on what a neighbour paid for their field ten years earlier. Seek a proper assessment, preferably in writing, that reflects planning status, access and possible future uses.
Once that figure is available, speak candidly with the friend or neighbour. If the arrangement is a real gift, describe it openly and accept that tax may apply above particular thresholds, particularly when the recipient is not a close relative. If it is partly a commercial opportunity, describe it as a sale or a long lease instead. A 25-year rural lease for bee pastures, with nominal annual rent, is often less damaging than a retrospective tax dispute.
The difficulty for many people is emotional. It can feel awkward to discuss money with a friend who merely wants to install a dozen hives. Not wishing to appear grasping, you may downplay the value or decide not to consult a notary. The arrangement remains imprecise, based on trust and memories of earlier times “when paperwork was simpler”.
Then circumstances change. The friend formalises the business, requires borrowing and registers the activity. The administration may connect the information long before you do. In reality, hardly anyone reads every line of notarial deeds or tax notices day after day. A signature is made, the file is put away and, years later, the consequences return in the most unfavourable form.
“People come to me saying, ‘I just wanted to help him with his bees,’” confides a notary from Deux-Sèvres. “They discover that generosity doesn’t protect them from legal form. The law sees flows of assets, not good intentions.”
- Obtain a written valuation of the land before any transfer, including one for a “symbolic” price.
- Look at long leases or usufruct arrangements rather than outright gifts.
- State the project’s true nature: a hobby, micro-business or fully commercial activity.
- Retain every email, sketch and note that demonstrates the arrangement’s original intention.
- Ask directly what would happen if the project expands or the land is sold on.
Why bee pastures in France now prompt major questions
Behind the legal details is a wider tension in France. Ageing landowners hold hectares that they no longer cultivate, while younger people hope to plant trees, keep sheep, install hives and experiment with agroecology. This intersection ought to renew the countryside. Instead, it frequently becomes a minefield of forms, suspicion and retrospective penalties.
Neighbours are beginning to ask whether anyone will risk sharing land in future if helping a friend start out can be considered “speculation in disguise”. Some are quietly choosing not to lend fields any more, even for community gardens, because they fear that tax officials could one day treat generosity as a scheme. Others continue regardless, but with the persistent anxiety of receiving a brown envelope.
| Key point | Detail | Value for the reader |
|---|---|---|
| Clarify intentions early | Set out whether the deal is a genuine gift, sale or lease, and record it in writing | Lowers the risk of reclassification and back taxes years afterwards |
| Know the land’s real value | Use a robust valuation that accounts for planning status and potential use | Prevents “symbolic” prices from appearing to be disguised tax avoidance |
| Choose simpler legal tools | Long leases, usufruct or occupation agreements for bee pastures | Makes it possible to help a friend without surrendering full ownership or peace of mind |
FAQ:
Question 1 Can a straightforward verbal agreement allowing beehives on my land create tax issues later?
Yes. The administration may identify the land’s actual use through registrations, photographs or subsidies. If subsequent formalisation exposes an earlier “hidden” transfer or undervalued arrangement, the tax authorities can revisit and reassess the entire situation.Question 2 Is land given to a non-relative always subject to high tax in France?
Gift tax between people who are not close relatives becomes high once a small allowance has been exceeded. The central concern arises when the declared value does not reflect reality, or when a profitable use follows quickly, creating suspicion of disguised speculation.Question 3 Is a long rural lease for bee pastures safer than a donation?
Often, yes. A lease leaves ownership with the pensioner, provides the beekeeper with legal use and avoids a substantial one-off transfer that must be valued and may be taxed as a gift or sale. It can remain symbolic while being clear.Question 4 Could I face an accusation of “abuse of law” merely because I undervalued my land?
A low price alone is insufficient. But where the administration finds evidence that you knew the land was worth more, or that the arrangement was primarily designed to avoid tax, it may claim abuse of law and impose penalties.Question 5 What should I do if I have already “gifted” land informally for a small ecological project?
Gather all documents, messages and evidence showing your original intention, then consult a notary or tax adviser before the project develops further. In some cases, putting the position right early through a corrected value or a new lease is less painful than waiting for a tax audit.
Comments
No comments yet. Be the first to comment!
Leave a Comment