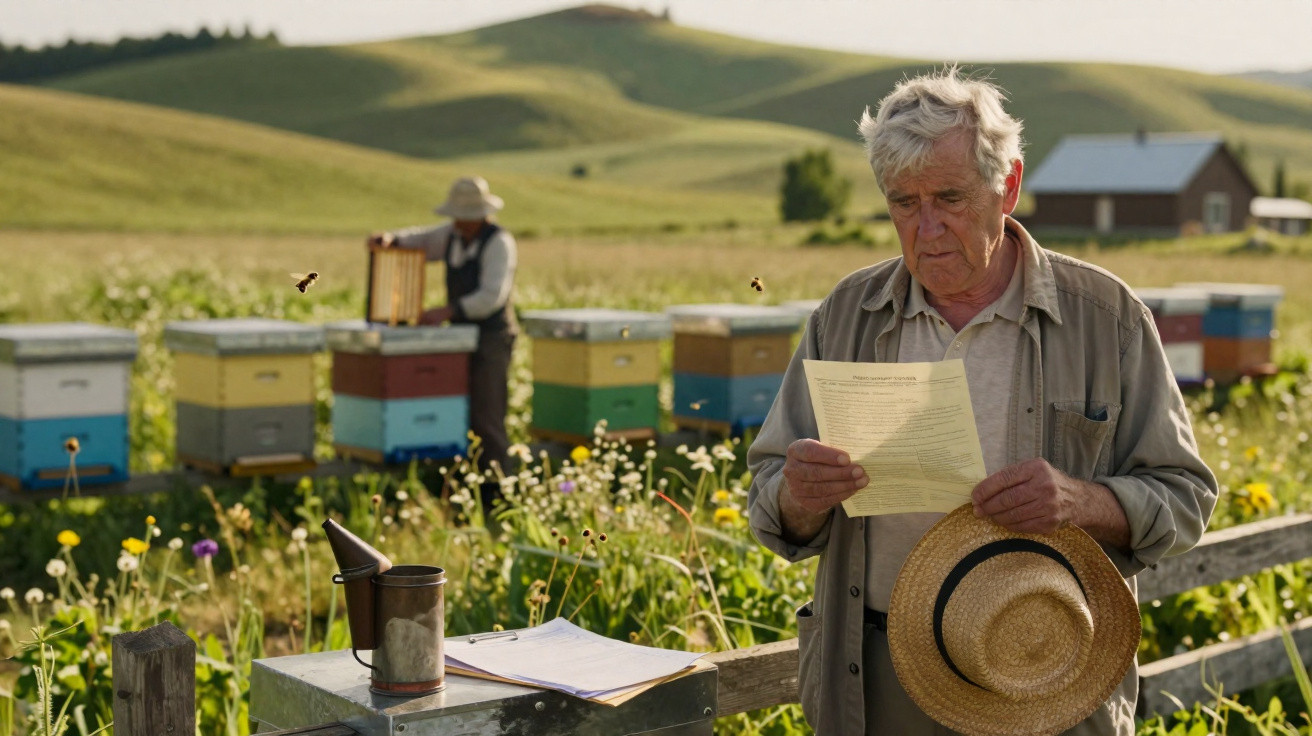
At the edge of the village, the first thing that reaches you is the sound: a gentle, continuous buzz rising from orderly rows of white wooden boxes, arranged like small apartment blocks for bees. Then there is the man moving slowly beside the hives, hands buried in his pockets and shoulders slightly rounded, as though he owes the landscape an apology for something beyond his understanding. This plot was meant to offer peace after a lifetime of work. He planned to let a young beekeeper use a stretch of green land, make a modest contribution to biodiversity, and perhaps provide honey for his grandchildren. Then a brown envelope arrived. It did not contain thanks, but a tax demand large enough to wipe away his smile.
He brushes his hand across a worn fence post and says, “I’m not making a cent from this.” The bees continue their work. So does the tax office. In an instant, an act of kindness has become a bureaucratic tempest.
When a few beehives make your retirement a “farm”
Written down, the situation seems almost ridiculous. A widowed retired teacher living on a modest pension lets a local beekeeper use several hectares of unused land. There is no rent, no agreement drafted by an expensive solicitor, only a handshake and a mutual conviction that the countryside ought to remain alive. A few months later, however, the tax administration redesignates her land as “agricultural exploitation”. Opening its letter, she finds a fresh farm tax demand, applied retrospectively and increased by penalties.
Her experience is far from unique. Throughout rural areas, small landowners allowing hives, sheep or vegetable plots on their fields are encountering this uncertain territory. Environmental policy promotes pollinators, local supply chains and organic honey. Tax rules, meanwhile, can treat regular productive use of land as professional agriculture. Consequently, pensioners and owners of limited means are caught in a legal framework they never anticipated, said to be operating a “farm” they do not even regard as their own.
The reasoning is simple, but unforgiving. Bees are active, honey is sold and the land is therefore viewed as being put to economic use. To the administration, those facts satisfy the conditions for a taxable activity. It carries little weight that the owner receives no money, that the beekeeper may be struggling to get by, or that the arrangement began as a gesture of solidarity. The tax code doesn’t care if your decision came from generosity or from greed. It recognises only use, classifications and thresholds. That is when the trouble starts.
Bureaucratic sting: who is the real “farmer” here?
On a misty Tuesday morning, the beekeeper leaves his van beneath a bent oak tree and raises a hive lid as though unlocking a safe. The retiree watches from a distance as the air fills with a golden haze. Their arrangement is as straightforward as the equipment they use. He gains a secure site away from pesticides, while she feels she is helping with a quiet rural stand against declining bee numbers. Then a tax inspector arrived, walked around the boundary with a clipboard and counted the hives as if they were tractors.
The inspection took under an hour. There were several questions, a handful of photographs and courteous remarks delivered with knife-like precision. Weeks later, she was told that dozens of hives remaining on her property year after year might be classed as an organised activity. The system drew no distinction between a multinational agribusiness leasing land and a pensioner allowing a young apiarist to place boxes beside a hedge. Both faced the same tax classification, obligations and threat of surcharges for “forgetting” to declare.
At the heart of the matter lies a stark reality: the system is not built for nuance. You either fit within a category or you do not. Land is either inactive, or considered productive and fed into the tax machine. That is how a well-meaning favour turns into a case reference. It is also why opinions in the countryside are divided. Some insist that “rules are rules, everyone must pay their share”. Others argue that penalising small acts of environmental solidarity is the surest way to end them. The law speaks one language; everyday life uses another.
How to prevent a good deed becoming a tax nightmare
Behind every brown envelope is often an informal arrangement that was allowed to drift too far. For anyone lending land to a beekeeper without wanting to be caught out, the first measure is rather unexciting: put the terms in writing. A basic agreement should make clear that the landowner receives no rent, no portion of honey sales and no concealed advantage, apart from perhaps a few jars offered as a friendly present. Such a document will not remove every risk, but it provides evidence to show an uncertain inspector.
It also helps to keep the operation modest and clearly “non-professional”. Two hives behind a barn create a very different impression from lengthy rows covering an entire field. Restrict the area involved, vary the use of the land and retain records of conversations about the beekeeper’s own professional registration. If an issue arises, the key question will be who is genuinely carrying out the economic activity: the person with a business number and invoices, or the person with a pension and a grassy field?
In truth, almost nobody reads tax legislation line by line before agreeing to help a neighbour install hives. Most people rely on trust, custom and the old rural instinct of “we’ll sort it out if there’s a problem”. That is precisely how they can be squeezed between rigid regulations and local common sense. There can also be a lingering sense of shame: the stubborn feeling that helping someone has somehow become wrongdoing.
“I’ve spent my whole life paying my taxes on time,” the retiree says. “Now they’re treating me like I’m hiding some kind of industrial farm. I don’t even like paperwork. I just wanted the bees to survive.”
- Request written confirmation from the tax office or local authority before placing hives or animals on your land.
- Retain evidence that the beekeeper is the registered professional and that you are not a partner in their business.
- Reduce the intensity and obvious scale of activity on your plot if you wish to avoid being placed in the “farm” category.
- Speak early to a local farmers’ union or landowners’ association; they often understand the practical thresholds that lead to inspections.
- Keep every letter, email and note: if a dispute arises, even the smallest dated record can become invaluable.
Most people know the feeling: a straightforward favour suddenly appears to be a legal snare that was never visible beforehand.
A country divided between bees, rules and common sense
This is about much more than one pensioner, one beekeeper or one village. It lies where three competing pressures meet. Environmental policies encourage people to support biodiversity, pollinators and shared gardens. Tax policy treats repeated productive activity as a taxable enterprise. Social reality shows that pensions are limited, small-scale beekeepers are vulnerable and rural communities are weary of being viewed as spreadsheets rather than places with histories and people.
Some readers will be angry: with the administration, with “free riders”, or with a system that appears to punish generosity while rewarding those who operate close to the limits of the rules. Others will see necessary discipline, intended to prevent abuse and undeclared earnings disguised as environmental action. Between those positions is a broad grey area inhabited by real people lending out corners of fields, swapping eggs for honey or cutting a neighbour’s meadow, never realising that they may be approaching the boundaries of agricultural law.
This is where the discussion becomes awkward. When do a few hives become a farm? Is a jar of honey given at Christmas considered payment? Should legislation create a “solidarity use” category for land, acting as a buffer between leisure and professional exploitation? While those matters remain unresolved, every new letter sent to a retiree who “isn’t making a cent from this” will feel like a warning to everyone else. Be generous with your land, and you may end up paying for it. Literally.
| Key point | Detail | Value for the reader |
|---|---|---|
| Identify your status early | Confirm in writing that you are a private landowner, rather than a business partner in the beekeeper’s activity | Avoid an unexpected reclassification as a “farm” and retrospective taxes |
| Limit and document the activity | Keep the arrangement modest and retain agreements, photographs and dates | Create a practical file to support your position if an inspection takes place |
| Seek local advice before acting | Speak to the council, tax office or an agricultural adviser before hives are installed | Identify legal and tax risks early instead of responding in panic later |
FAQ:
- Question 1 Can lending land for beehives really turn me into a “farmer” for tax purposes?
- Answer 1
- Yes. In certain jurisdictions, repeated and organised production on your land may result in an agricultural or professional classification, even where you receive no direct income. This is why written agreements and clearly defined roles are important.
- Question 2 Does receiving a few jars of honey count as income?
- Answer 2
- Infrequent symbolic gifts are generally treated as non-commercial. However, substantial and regular amounts, or a systematic “exchange”, could be viewed as payment in kind and prompt questions during an inspection.
- Question 3 How many hives are “too many” before tax rules change?
- Answer 3
- No single universal number exists. Limits differ between countries and regions, while tax inspectors also consider regularity, the area used and whether the activity forms part of a registered business.
- Question 4 Can a simple handwritten agreement with the beekeeper really help?
- Answer 4
- Yes, it may help. It cannot override the law, but it demonstrates the intention: no rent, no profit-sharing and no concealed business. Alongside other paperwork, it can support your case.
- Question 5 What should I do if I’ve already received a tax bill like this?
- Answer 5
- Act promptly: ask the tax office for a meeting or written explanation, collect every document concerning use of the land and consult a legal or agricultural adviser. Once the circumstances are explained, reassessment or partial cancellation can sometimes be possible.
Comments
No comments yet. Be the first to comment!
Leave a Comment